Wired to Buy High: The Behavioral Finance Patterns Costing American Crypto Investors the Most
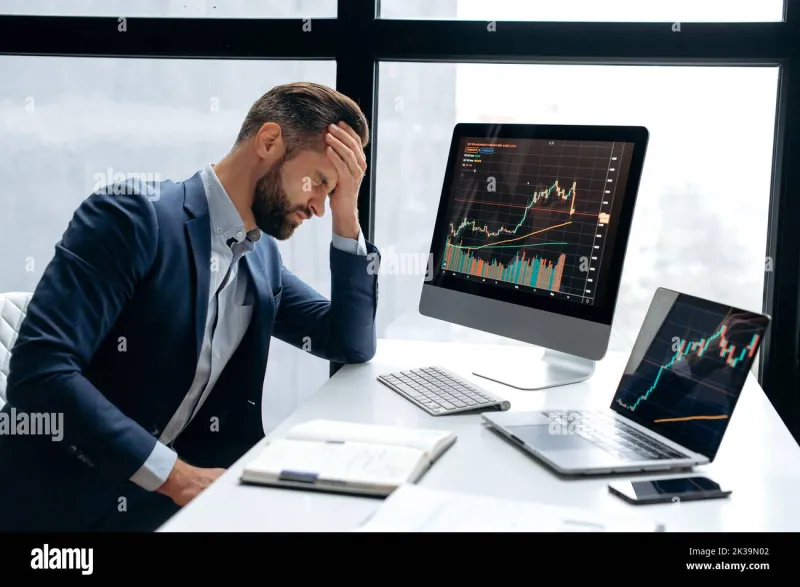
Photo: stressed investor watching cryptocurrency price chart on computer screen, via c8.alamy.com
The pattern is almost ritualistic at this point. Bitcoin climbs toward a new all-time high, mainstream media coverage intensifies, social media feeds fill with screenshots of unrealized gains, and millions of Americans who had been watching cautiously from the sidelines decide that now — finally — is the moment to get in. Within weeks or months, the correction arrives. Portfolios shrink. Resolve evaporates. And the cycle prepares to repeat itself.
This is not a story about market manipulation or irrational exuberance in the abstract. It is a story about the human brain encountering an asset class it was never designed to evaluate, and the predictable failures that follow.
The Anatomy of a FOMO-Driven Buy
Fear of missing out — FOMO — has been studied extensively in consumer psychology, but its expression in cryptocurrency markets carries a particular intensity. Unlike traditional equities, digital assets operate across continuous, 24-hour global markets with no circuit breakers and no closing bell. Price movements are visible at all hours. Gains accumulate and evaporate in real time. The psychological pressure this creates is qualitatively different from watching a brokerage account update once a day.
Research from behavioral economists, including work building on Daniel Kahneman and Amos Tversky's foundational prospect theory, consistently shows that humans weight potential losses more heavily than equivalent gains. In a rising market, however, this calculus inverts in a damaging way: the perceived loss of not participating begins to feel more acute than the rational risk of entering at an elevated price. The brain reframes inaction as a loss, and action — even poorly timed action — as relief.
For American retail investors specifically, this dynamic is amplified by a cultural narrative around wealth-building that prizes bold moves and early adoption. The stories that circulate most widely are not about disciplined, dollar-cost-averaged accumulation. They are about the person who bought in 2017, or 2020, or during some other pivotal window, and became financially transformed. These stories compress the timeline and obscure the volatility endured along the way.
Why Awareness Alone Fails as a Corrective
One of the more frustrating findings in behavioral finance is that understanding a cognitive bias does not reliably protect against it. Surveys of retail crypto investors in the United States routinely find that a significant majority are aware of boom-bust cycles, acknowledge that timing the market is difficult, and still report making purchases driven primarily by price momentum rather than fundamental analysis.
This gap between knowledge and behavior is explained in part by what psychologists call the affect heuristic — the tendency to make decisions based on emotional state rather than deliberate reasoning. When an asset is rising sharply and one's social environment is saturated with positive signals about it, the emotional valence of the decision shifts. Buying feels good. Waiting feels anxious. The analytical framework that an investor might apply in a calmer moment becomes harder to access when dopamine-driven excitement is running high.
There is also the matter of social proof. In a market where prices are driven substantially by collective sentiment, seeing others profit creates a feedback loop. The more people buy, the more prices rise; the more prices rise, the more people buy. Rational observers who recognize this dynamic intellectually may still find themselves drawn in, partly because they cannot be certain where in the cycle they actually stand.
The Recency Bias Problem in Volatile Markets
Recency bias — the tendency to weight recent events more heavily than historical patterns — is particularly destructive in cryptocurrency markets because of how extreme recent events tend to be. An investor who enters the market during a bull run experiences weeks or months of upward price movement as their primary data set. That recent experience feels more real and more informative than a historical chart showing multiple 70 to 80 percent drawdowns.
This is compounded by the relatively short history of digital assets as an investable class. American investors who began paying attention to crypto after 2020 have lived through a compressed and dramatic series of cycles. The psychological anchoring that occurs around the prices and conditions one first encounters in a market can distort risk perception for years afterward.
When prices eventually correct — as they have, without exception, following every major crypto rally — recency bias reverses. The recent loss becomes the dominant psychological reference point. Investors who bought at the peak and are now holding at a significant loss face a different but equally dangerous set of impulses: holding too long in the hope of a return to their entry price, or capitulating at the worst possible moment to escape further pain.
Practical Frameworks for Interrupting the Cycle
Acknowledging the psychological mechanisms at work is a necessary first step, but it is not sufficient. Several practical approaches have demonstrated effectiveness in helping investors impose structure on emotional decision-making.
Pre-commitment strategies involve establishing investment rules in advance and in writing, before market conditions become emotionally charged. Deciding, for example, that you will invest a fixed dollar amount on a fixed schedule regardless of current price removes the moment-to-moment decision from the emotional environment in which it would otherwise occur. Dollar-cost averaging, while often dismissed as insufficiently sophisticated, functions as precisely this kind of pre-commitment mechanism.
Cooling-off periods represent another structural intervention. Some investors commit to a mandatory waiting period — 48 or 72 hours — between the impulse to make a significant purchase and the execution of that purchase. This interval allows the initial emotional charge to dissipate and creates space for more deliberate analysis.
Separation of signal from noise is perhaps the most demanding discipline. In a market environment where price movement, social media commentary, and news coverage are deeply intertwined, distinguishing between information that genuinely updates one's assessment of an asset's value and information that simply reflects current sentiment is difficult. Developing a personal checklist of questions to answer before any significant purchase — questions about on-chain fundamentals, protocol development activity, macroeconomic conditions, and one's own financial position — can serve as a forcing function for this kind of analysis.
Portfolio allocation limits function as a hard boundary against the concentration risk that FOMO-driven buying tends to produce. Committing in advance to a maximum percentage of one's investable assets in any single digital asset, and treating that ceiling as non-negotiable during periods of market excitement, prevents the kind of over-exposure that transforms a bad trade into a financial crisis.
The Structural Challenge That Remains
It would be convenient to conclude that better investor education or improved self-awareness will substantially solve the problem of poorly timed crypto purchases. The evidence, however, suggests that individual behavioral interventions have limits. The structural features of digital asset markets — continuous trading, social media amplification, narrative-driven price discovery — are not incidental to the problem. They are, in important respects, the problem.
For American retail investors operating in this environment, the most realistic goal may not be the elimination of emotionally influenced decisions but rather the reduction of their frequency and scale. Building systems that create friction between impulse and execution, maintaining realistic expectations about one's own susceptibility to market psychology, and treating behavioral discipline as an ongoing practice rather than a solved problem are the unglamorous foundations of more durable portfolio outcomes.
The market will continue to generate peaks. The social and psychological machinery that draws investors toward those peaks will continue to operate. The question is whether individual investors can build enough structural resistance to keep the damage manageable when the inevitable correction arrives.